Setting financial goals that feel achievable starts with understanding personal priorities and breaking down larger targets into smaller, manageable steps. Clear, realistic goals matched to one’s current situation make the path forward less overwhelming and easier to follow.
They should focus on specific amounts and timeframes while allowing flexibility for unexpected changes. This approach helps maintain motivation and tracks progress effectively without causing unnecessary stress.
By aligning goals with actual income, expenses, and lifestyle, individuals can create plans that are both ambitious and within reach. Taking this balanced approach encourages steady advancement toward financial stability.
Understanding Financial Goals
Financial goals guide individuals through their financial journey by providing structure and clarity. They should be realistic, timely, and relevant to one’s current financial situation. Breaking down goals into manageable parts helps maintain focus and motivation.
What Makes a Goal Achievable?
An achievable financial goal is specific, measurable, and aligned with the person’s income and expenses. It requires clear deadlines and actionable steps, such as saving a fixed amount monthly rather than vague targets like “save more.”
Feasibility depends on understanding personal financial limits and avoiding overambitious plans. For example, aiming to pay off $5,000 in credit card debt in six months is more realistic than expecting to clear $30,000 in the same period without increasing income.
Regularly reviewing financial progress also ensures goals stay attainable. Adjustments may be necessary when income changes or unexpected expenses arise.
Short-Term, Mid-Term, and Long-Term Goals
Financial goals fall into three categories:
| Goal Type | Time Frame | Examples |
| Short-Term | Up to 1 year | Building an emergency fund, clearing small debts |
| Mid-Term | 1 to 5 years | Saving for a car, home down payment |
| Long-Term | 5+ years | Retirement savings, paying off mortgage |
Short-term financial goals help establish good habits and create quick wins. Mid-term goals bridge daily finances and larger aspirations. Long-term financial goals provide direction for sustained financial security and wealth building.
Balancing these goals avoids neglecting urgent needs or future planning. Each type plays a key role in overall financial health.
The Importance of Goal Setting
Goal setting creates a roadmap for managing money effectively. It helps prioritize spending, saving, and investing based on individual financial objectives.
People who set clear financial goals tend to track their progress and make better financial decisions. This reduces impulsive purchases and helps stay focused on outcomes like debt reduction or wealth accumulation.
Moreover, well-defined goals improve motivation and discipline. They act as benchmarks to celebrate milestones and adapt strategies when necessary, reinforcing control over one’s financial situation.
Steps to Setting Achievable Financial Goals
Setting financial goals requires a clear understanding of one’s current money situation, specific objectives, and a structured method to ensure those goals are practical and measurable. This process helps in creating a plan that supports long-term financial stability and growth.
Assess Your Financial Health
The first step is evaluating the current financial status. This involves reviewing income, expenses, debts, and assets, including any existing investment portfolio. A clear picture of monthly cash flow and net worth helps identify where money is going and what can be adjusted.
Checking credit reports and outstanding debt provides insight into financial obligations that may affect goal-setting. Understanding financial health ensures goals are realistic and aligned with the ability to save or invest. Without this assessment, setting practical goals is difficult.
Define and Prioritize Your Objectives
Once financial health is understood, specific goals must be defined. These can include saving for emergencies, paying down debt, investing for retirement, or funding education. Prioritizing these goals is crucial; goals with immediate impact or deadlines should come first.
He or she should list goals by importance and timeline, recognizing that some goals may require more immediate attention or resources. Prioritization helps focus efforts and avoid spreading resources too thin across too many ambitions.
Apply the SMART Goals Framework
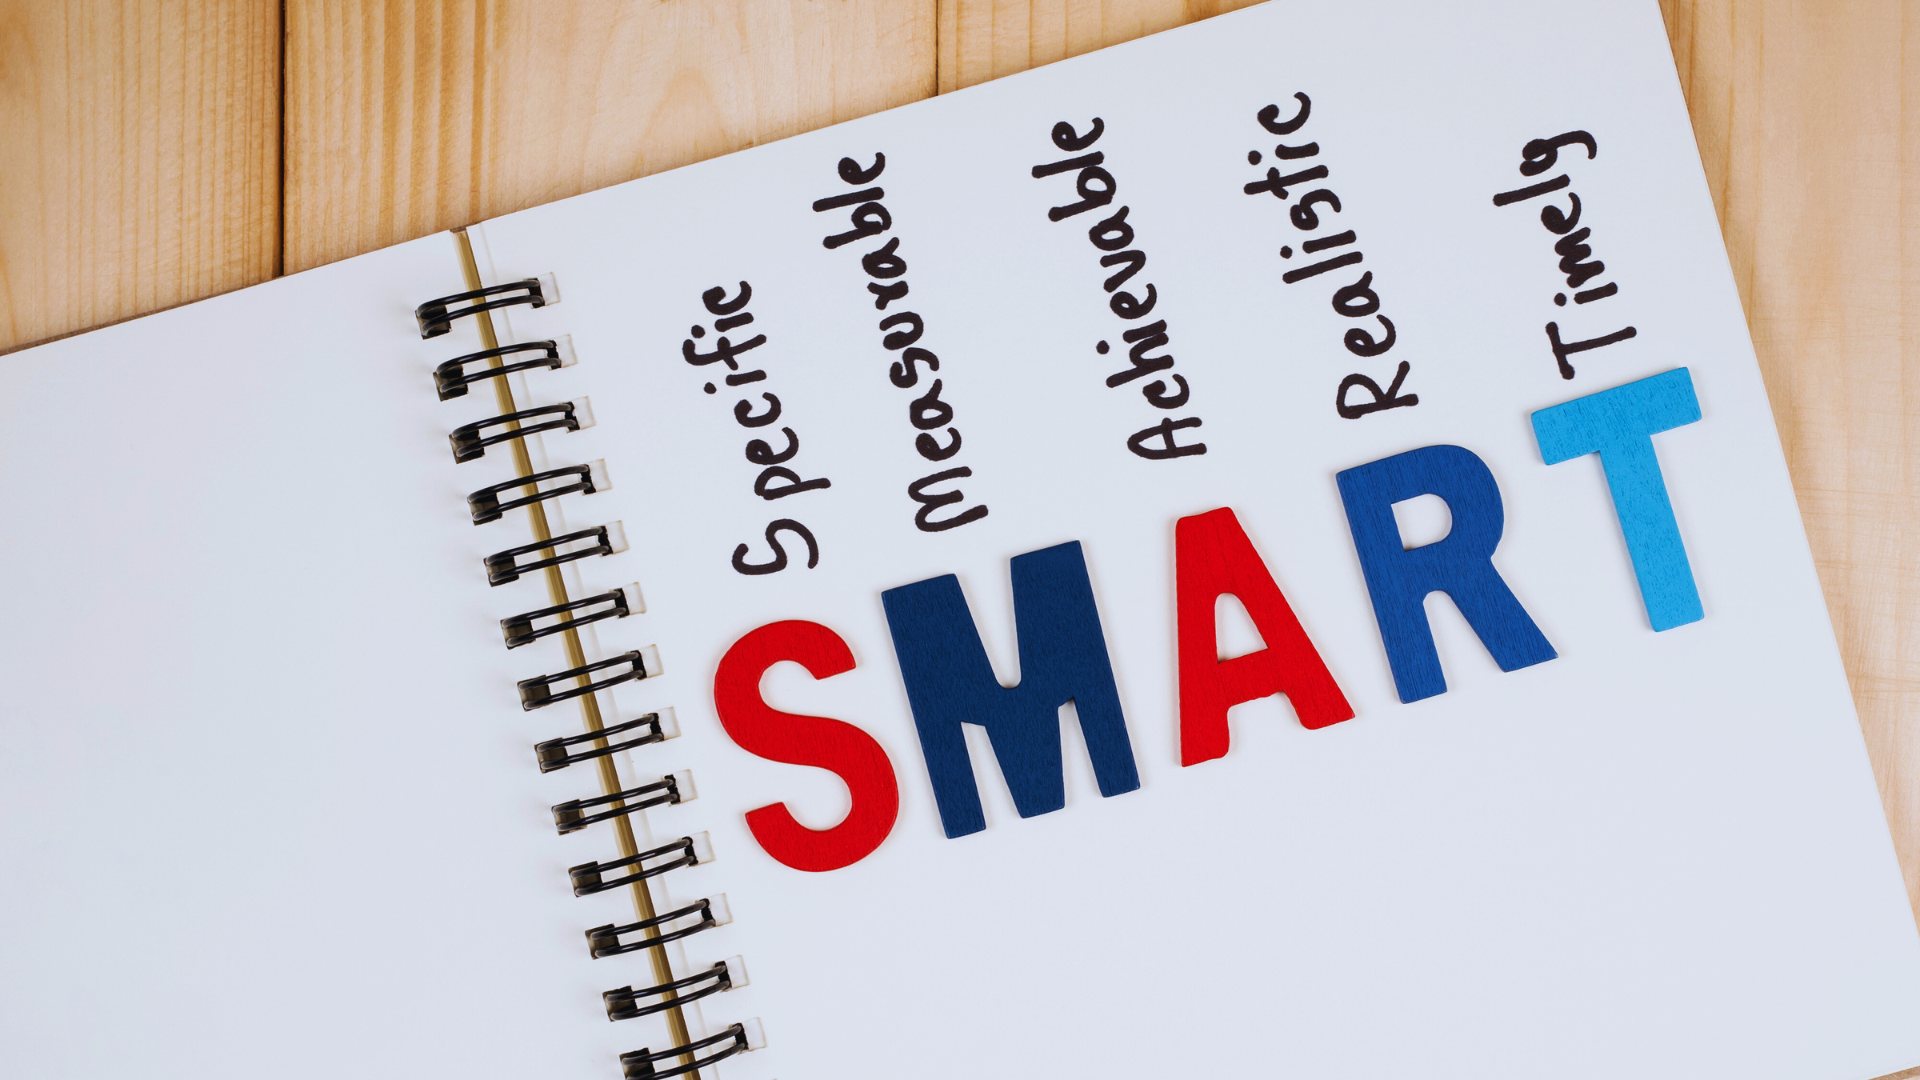
Using the SMART framework—Specific, Measurable, Achievable, Relevant, Time-bound—adds clarity and structure. Goals like “Save $5,000 for an emergency fund in 12 months” are better than vague aims such as “Save more money.”
Each goal should include measurable milestones, remain realistic based on financial health, and link directly to the person’s long-term financial future. Time constraints keep progress on track and encourage regular review and adjustment. This approach increases the likelihood of success.
Building a Strong Financial Foundation
A solid financial foundation begins with clear, manageable steps in budgeting, saving, and debt repayment. Each part supports the others, making it easier to reach specific money goals without feeling overwhelmed.
Developing a Realistic Budget
Creating a monthly budget starts with tracking income and expenses precisely. He or she should list all sources of income and categorize every expense, distinguishing between essentials like rent and discretionary spending.
Using budgeting apps can simplify this process by automatically organizing transactions and alerting the user about overspending. The goal is to set spending limits that align with income while allowing flexibility for small savings.
A realistic budget prioritizes saving money by allocating a defined amount each month toward financial goals. It should be reviewed regularly to adjust for changes in income or expenses.
Establishing an Emergency Fund
An emergency fund acts as a financial safety net for unexpected expenses such as car repairs or medical bills. It is generally recommended to save enough to cover three to six months of essential living costs.
Funds should be kept in an easily accessible account, like a high-yield savings account, to earn some interest while remaining liquid. Contributions to this fund can be small but consistent until the target amount is reached.
Having a dedicated emergency fund reduces the need to rely on credit cards or loans during financial setbacks, preserving credit health and reducing stress.
Paying Off Debt Strategically
Prioritizing debt repayment improves financial stability and frees up resources for future goals. High-interest debt, especially credit card debt, should be addressed first to minimize interest costs.
One common approach is the debt avalanche method, focusing payments on the highest interest rates while maintaining minimum payments on others. Alternatively, the debt snowball method targets the smallest balances first to build momentum.
Student loan debt also requires attention, balancing repayment with savings. Automating payments can prevent missed deadlines and sometimes qualify for interest reductions. Being strategic about paying off debt ensures faster progress toward financial independence.
Reaching and Adapting Your Financial Goals
Effectively managing financial goals involves selecting appropriate accounts, regularly tracking progress, and recognizing key achievements. Each step contributes to maintaining motivation and ensuring long-term success, especially when targets like saving for a down payment or preparing for early retirement are involved.
Choosing the Right Savings and Investment Accounts
Selecting accounts that match specific financial goals is critical. For short-term goals, such as accumulating a down payment on a house, high-yield savings accounts or certificates of deposit (CDs) can offer safety and steady returns. CDs typically provide higher interest than regular savings but require funds to stay locked in for a fixed term.
For long-term objectives like saving for retirement, accounts such as a 401(k) or IRA are more suitable. These accounts offer tax advantages and investment options that support growth over decades. Deciding between traditional and Roth versions depends on expected tax situations.
Diversifying across account types ensures liquidity for near-term needs while optimizing growth for distant goals like early retirement or mortgage payoff.
Tracking Progress and Adjusting as Needed
Consistent monitoring is essential to stay on track. Using budgeting tools or financial apps helps track contributions, interest earned, and investment performance. For example, reviewing 401(k) statements quarterly provides insight into retirement plan growth and determines if adjustments are necessary.
If progress slows due to market shifts or life changes, adapting goals or strategies is vital. This might mean increasing monthly savings, reallocating investments for better returns, or extending the timeline. Flexibility allows goals such as mortgage payoff or reaching a retirement fund target to remain realistic.
Regular reviews prevent surprises and promote timely decisions, ensuring goals remain achievable without undue stress.
Celebrating Milestones
Recognizing financial milestones reinforces positive habits. Achieving the first $5,000 in a savings account for a down payment or hitting a contribution target in a 401(k) warrants acknowledgement. Celebrations can be simple, like a small reward or sharing progress with close friends or family.
Acknowledging progress in stages breaks down what might feel like overwhelming goals into manageable parts. This boosts confidence and encourages continued commitment to saving, whether for retirement or mortgage payments.
Tracking and celebrating milestones also provide motivation during setbacks, helping maintain focus on long-term financial health.

Leave A Comment